Who this card is for
A good fit if you…
- National Bank customers who will carry a purchase balance and whose interest savings versus a 20%-class rewards card will clear $35.
- People who want a Mastercard at Costco while they de-lever, without pretending MC1 is a rate card.
- Anyone who compared Flexi’s $0 10.90% Visa and would rather stay at National Bank on Mastercard — run the $35 versus two points of rate on your leftover.
- Applicants who understand there is no 0% teaser on Syncro.
Skip it if you…
- Anyone who pays in full. An 8.90%-class rate does nothing if you never pay interest; mycredit or ECHO currently lists cash back for that habit.
- People who needed a 0% transfer window. MBNA True Line currently lists one at $0; Syncro does not.
- Rewards collectors. There is no rewards program.
- Anyone chasing a welcome bonus. None is currently listed.
Pros and cons
Pros
- The purchase rate is the lowest National Bank consumer rate on this site and undercuts True Line Gold and Flexi on the rate line (Flexi still wins on fee).
- The product is categorized and described as a balance card — fewer surprises than MC1’s category mismatch.
- Mastercard acceptance includes Costco Canada, unlike Flexi’s Visa.
- There is no fake grocery mix to distract you from paying the card down.
- You stay in the National Bank app rather than opening MBNA or Desjardins if this is already the bank.
Cons
- A $35-class fee has to be earned on rate savings. Flexi currently lists 10.90% at $0 on a Visa — Syncro can lose if the leftover is small.
- No welcome bonus, extra-card fees, eligibility terms, or insurance are currently listed. Year-one value is $35 versus 8.90%.
- There is no 0% purchase or transfer teaser.
- Cash-advance interest is 12.90%-class — better than many cash-advance rates, still not a reason to take cash.
- National Bank’s footprint is strongest in Quebec.
Fees and value: is the annual fee worth it?
First-year snapshot (estimate)
- Annual fee
- $35
- Estimated welcome bonus value
- Not listed
- Bonus minus fee (estimate)
- —
This is a simple comparison of the estimated welcome-bonus value against the annual fee. It ignores rewards on spending, credits you have to remember to use, and interest if you carry a balance. Offers change — verify with the issuer.
The fee table shows a $35-class card; extra-card fees are not listed. There is no welcome-bonus value, so the first-year snapshot will look like a fee with no bonus — correct.
Year one and year two are $35 versus 8.90%. On a $4,000 leftover versus a 20.99% rewards card, the rate gap dwarfs $35.
Versus Flexi’s 10.90% at $0, two points on a $2,000 leftover is about $40 — Syncro and Flexi are close; pick the bank and network you need. If you pay in full, mycredit or ECHO is the better National Bank card.
If you needed a 0% transfer, True Line currently lists that shape. Offers change.
Pay the balance down. Syncro is not permission to revolve forever.
Rewards and earn rates explained
Rewards program: N/A
This card does not pay À la carte Rewards or cash back. Rewards currently say N/A; features currently describe a low-interest Mastercard with no rewards program.
Put a revolving balance here. Put restaurants and PAPs you pay in full on National Bank mycredit Mastercard.
Put grocery cash back on ECHO. Put 2x grocery/dining on Platinum.
Costco will take this Mastercard; warehouse spend still accrues at 8.90% with no earn mix.
Welcome bonus: how to unlock it
No welcome bonus is currently listed for this card.
This card currently lists no welcome bonus, detailed offer, dollar value, or eligibility text. Treat that as “none on file.” If National Bank is running a 0% window on the Syncro application page, use that page. Do not copy True Line’s 12-month transfer teaser onto this card.
FAQ
Is the National Bank Syncro Mastercard worth it in 2026?
It is worth it when you will carry a balance, 8.90% after $35 beats the card you have now, and you pay it down. It is not worth it as a cash-back card or as a card you pay in full.
Syncro vs MC1?
MC1 currently lists $0, no rewards, and a 20.99%-class purchase rate despite a Low Interest category. Syncro currently lists 8.90% at $35. Choose Syncro if interest is the problem. Choose MC1 if you wanted simple $0 plastic and pay in full.
Syncro vs Desjardins Flexi vs True Line Gold?
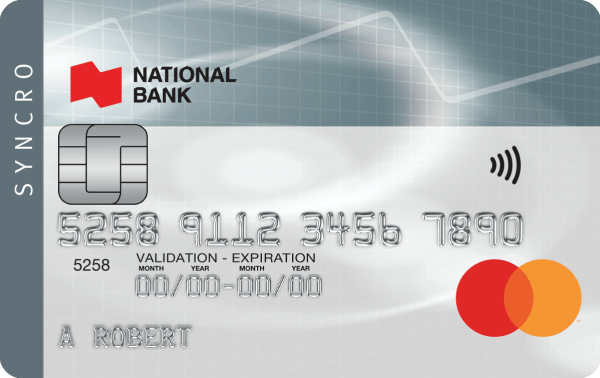
Flexi currently lists 10.90% at $0 on a Visa. True Line Gold currently lists 10.99% at $39 on a Mastercard. Syncro currently lists 8.90% at $35 on a Mastercard. Choose Syncro for the lowest ongoing rate in this trio if you bank at National Bank. Choose Flexi to avoid a fee. Choose True Line Gold if MBNA and Costco at 10.99% are enough.
Should I use this if I pay in full?
No. Pay in full on mycredit, ECHO, or Tangerine. Syncro’s only job is interest.
Does this card charge foreign-exchange fees?
Most Canadian low-rate Mastercards add a conversion fee on foreign-currency purchases. Syncro is a domestic rate card, not a no-FX travel card. Confirm National Bank’s current FX rate in the agreement.
Compare related cards and guides
More Canadian credit card lists that match this product, plus a few cards people usually compare it with.
- National Bank MC1 Mastercard review · National Bank · $0 annual fee
- Desjardins Flexi Visa review · Desjardins · $0 annual fee
- MBNA True Line Gold Mastercard review · MBNA · $39 annual fee